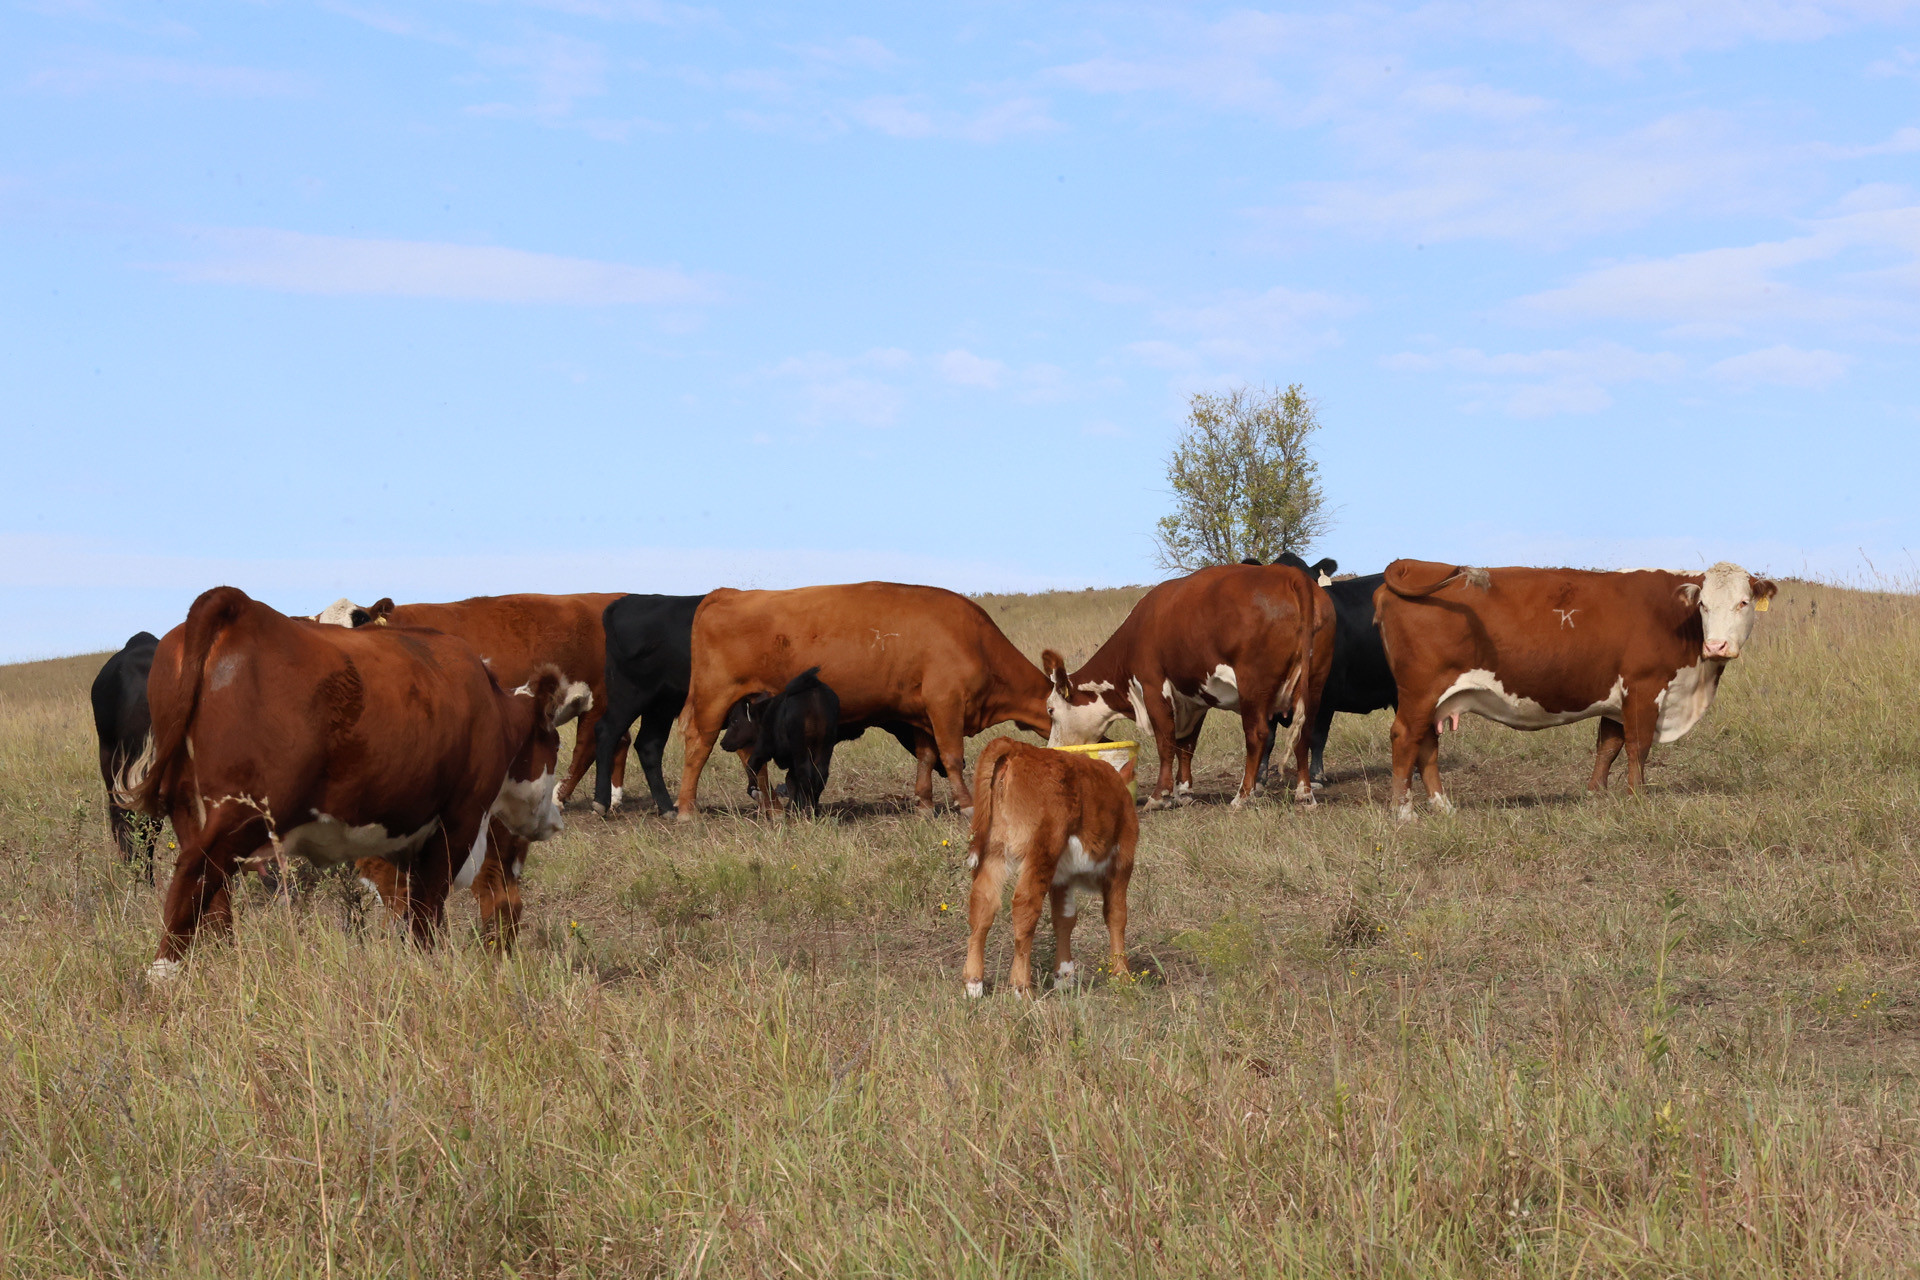
By now you are likely well versed in the narrative surrounding the cattle complex. A historically low United States cattle herd and strong domestic demand for beef lifted cattle futures prices to historic peaks in early 2026.
Front month cattle futures soared to $258.72 in April, testing the very top of the upward channel line that had been intact since 2020. May saw a very cautious tone, with prices then beginning to slide lower during June.
The selling continued, as live cattle futures prices then slid lower for most of summer, losing over $30 along the way. The bullish narrative had seemingly run its course, and cattle futures prices faded as profit taking by the fund traders emerged throughout summer.
Live cattle futures seemed to finally find firm footing during the month of September, with prices for the October 2026 contract bottoming near $210, and slowly gained more than $20 over the course of two months.
As the calendar now flips to November, what will traders be monitoring into year end? Will the uptrend resume? Or will prices begin to fade? Here are factors to monitor into year end.
From a marketing perspective
Take note, the U.S. cattle herd is not growing. Drought in much of the Plains during the summer of 2026 made it hard for producers to source feed, thus providing little incentive to hold heifers back for breeding. The lower sources of pasture for grazing due to drought also was a reason to send older cows to slaughter.
Because of the drought, cattle on feed reports from this summer showed that there were slightly larger cattle on feed numbers. Keep in mind, this was due to feeder cattle going into feedlots, (rather being put on pasture).
The most recent U.S. Department of Agriculture’s Cattle on Feed report confirmed that fact. Total cattle on feed was 11.37 million head, 100% of last year. Placements were at 1.777 million head, only 88% of last year. Placements into feedlots during September totaled 12.1% below year-ago levels, setting a record low for the month since the data series began in 1996. Heifer inventories were 4.3 million head, down 1% from last year.
Looking ahead, industry chatter is that future cattle on feed reports may likely continue to show lower cattle on feed numbers. Placement numbers are also expected to continue to be low, lending price support to the latter part of 2026 and early 2027. These factors should continue to be supportive to prices.
However, there are other factors at play that may keep a lid on prices in the short term.
Rising imports of beef has not been a secret. The current administration has encouraged it. Last month, President Donald Trump announced a plan to allow 300,000 metric tons of beef to enter the United States over a 90-day period without being subject to out-of-quota tariffs.
Overall imported fresh beef into the U.S. is up 15% year over year. That trend is expected to continue. We will likely import even more beef from Brazil and other South American countries into year-end (to meet President Trump’s 300,000 metric ton increase over 90 days).
Future consumer demand is in question. With high fuel prices at the gas pump and stubbornly high prices at the grocery store, will the consumer finally balk at higher priced beef and opt for cheaper protein? While demand for higher cuts of beef has been reduced slightly, demand for cheaper cuts of beef and ground beef remains strong.
America loves “Taco Tuesday” and grilling burgers at fall tailgates. The question heading into the holidays, with funds tight for many U.S. families, is if the consumer will purchase higher priced cuts of meat this year at holiday time?
Finally, a last major component of cattle futures prices has to do with the fund traders. Managed money funds have shed nearly 100,000 contracts from their peak earlier in 2026. As of the Oct. 20 commitment of traders’ report, managed money funds were long 51,143 contracts of cattle, down from the peak of 156,909 contracts. They shed more than 100,000 contracts during most of third quarter, to show profits on the books. Will they emerge as buyers or sellers into year end?
Prepare yourself
The cattle complex is at a crossroads. The U.S. herd is not rebuilding, but cheaper imports of beef are being brought into this country. Consumer demand has been strong, but will it remain strong into the holidays with families maybe opting to buy gifts, rather than high priced steaks. Will managed money fund traders begin to build back a long position? Or might they continue to liquidate the remaining portion of their long contracts?
The outcome over the next two months likely sets the tone for 2027. Be dialed in on the activity in the cattle complex. It matters.
If you have questions, you can reach Naomi at [email protected] or find her on X (formerly twitter) @naomiblohm.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Carefully consider whether such trading is suitable for you in light of your financial condition. Examples of seasonal price moves or extreme market conditions are not meant to imply that such moves or conditions are common occurrences or likely to occur. Futures prices have already factored in the seasonal aspects of supply and demand. Total Farm Marketing refers to Stewart-Peterson Group Inc., Stewart-Peterson Inc., and SP Risk Services LLC. Stewart-Peterson Group Inc. is registered with the Commodity Futures Trading Commission (CFTC) as an introducing broker and is a member of National Futures Association. Stewart-Peterson Inc. is a publishing company. SP Risk Services LLC is an insurance agency and an equal opportunity provider. A customer may have relationships with any of the three companies